

A divorce decree can state that one spouse will receive part of a retirement account, but that language alone may not give the retirement plan authority to divide the funds. For many employer-sponsored plans, the missing document is a Qualified Domestic Relations Order, commonly called a QDRO.
For couples with meaningful retirement savings, pensions, deferred compensation, or a long employment history, a QDRO can affect far more than paperwork. It can shape when benefits are paid, whether investment gains and losses are shared, how survivor benefits are addressed, and how the retirement division fits into the overall settlement.
What is a QDRO in an Arizona divorce?
A QDRO is a court order that tells an eligible employer-sponsored retirement plan to recognize and pay a defined share of a participant’s benefit to a spouse, former spouse, child, or dependent. It translates the retirement terms of an Arizona divorce settlement into instructions the plan administrator can accept and implement.
Federal law generally protects retirement-plan benefits from assignment. A QDRO is a limited exception that allows a plan to pay an “alternate payee,” often a former spouse, under the proper circumstances. The U.S. Department of Labor’s QDRO guidance explains that the plan administrator, not the family court, determines whether an order meets the plan’s qualification requirements.
In Arizona, the larger property agreement still matters first. Arizona law requires the court to divide community, joint, and other property equitably, which calls for careful attention to when retirement benefits were earned, any premarital balance, and the couple’s complete financial picture. You can review the governing property-division statute at Arizona Revised Statutes section 25-318.
Which retirement accounts need a QDRO?
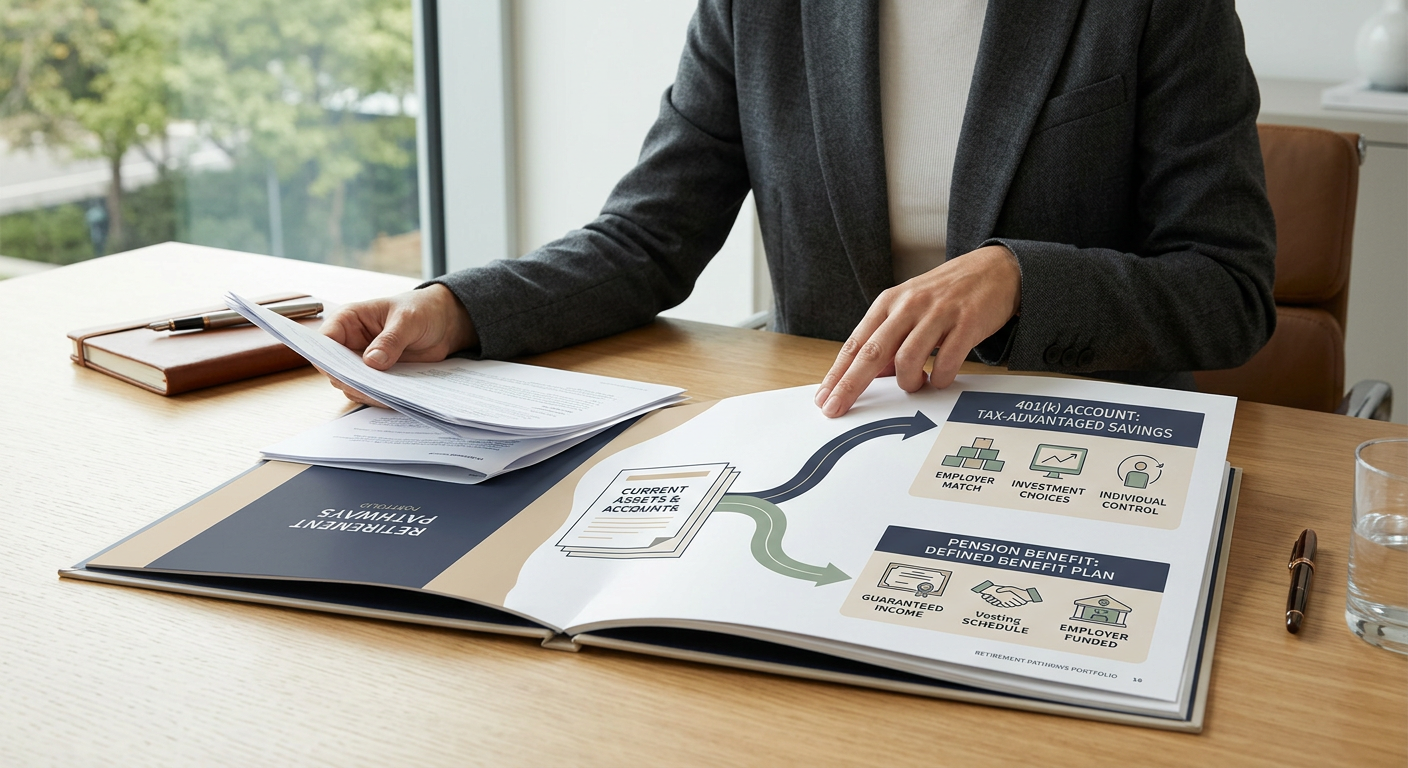
A QDRO is generally used for many private-sector employer plans, including 401(k) plans, profit-sharing plans, and traditional pensions governed by federal retirement-plan rules. The correct document depends on the particular plan, not merely on the account label.
That distinction is important because not every retirement asset is divided with a QDRO. A settlement may involve several accounts, each with its own rules and documents.
| Asset type | Typical division document | Important consideration |
|---|---|---|
| Private 401(k) or pension | QDRO | Plan administrator must approve it |
| IRA or Roth IRA | Transfer incident to divorce | Usually not a QDRO |
| Arizona public retirement plan | Domestic Relations Order | Plan-specific procedures apply |
| Federal civilian retirement | Court order acceptable for processing | Federal system has separate rules |
| Military retirement | Military-specific order | Federal requirements apply |
For example, the Arizona State Retirement System uses a Domestic Relations Order process and asks parties to submit a draft for review before submitting the certified final order. An IRA is different: the IRS explains that an IRA transfer incident to divorce can be completed through a trustee-to-trustee transfer, rather than a QDRO.
We encourage couples to create a complete inventory before making any agreement. That means identifying every retirement plan, obtaining plan statements and summary plan descriptions, and separating retirement questions from assumptions based on account names alone.
What must a QDRO say?
A QDRO must clearly identify the participant, the alternate payee, the applicable plan, and the amount, percentage, or calculation method for the assigned benefit. It must also state the number of payments or the time period covered, while staying within the benefits the plan actually offers.
A workable order often needs answers to questions such as:
- What portion is considered marital or community property?
- Is the former spouse receiving a fixed dollar amount, a percentage, or a formula-based share?
- Will the alternate payee share in investment gains and losses from a stated valuation date until distribution?
- For a pension, when can payments begin and how will the monthly benefit be calculated?
- Are survivor benefits, early-retirement subsidies, or cost-of-living adjustments relevant?
- Who will prepare the order, submit it for preapproval, file it with the court, and follow through with the plan?
The Maricopa County Superior Court’s divorce materials describe a QDRO as “a very specialized legal document” that requires professional assistance. That is sound practical guidance. A QDRO that conflicts with plan language, omits material terms, or does not match the settlement can be rejected or create a later dispute.
Why the QDRO should be addressed before the divorce is final
The best time to identify QDRO requirements is while the retirement division is being negotiated, not months or years after the decree is entered. Early coordination helps the settlement language, plan procedures, valuation date, and eventual order work together.
For financially established Arizona couples, retirement decisions rarely stand alone. One spouse may prefer to retain a larger 401(k) balance while the other keeps more home equity, brokerage assets, or cash. A pension may have no obvious current account balance, yet represent an important future income stream. A physician, executive, or business owner may also have a mix of qualified accounts, deferred compensation, equity compensation, and nonqualified benefits that need separate treatment.
That is why we look at retirement in the context of the whole balance sheet. Our financial expertise during divorce can help couples evaluate liquidity, taxes, cash flow, and long-range retirement planning before they choose how to equalize the estate.
Considering retirement division as part of an Arizona divorce? If your agreement involves a pension, substantial 401(k) assets, multiple plans, or competing financial priorities, schedule a private consultation with Modern Mediation to discuss how a thoughtful mediation process can organize those decisions.
How does a QDRO process typically work?
Although each plan has its own procedures, the process typically moves from settlement design to plan review, court entry, and implementation. The retirement division is not complete merely because the decree mentions an account.
- Identify the plan and obtain its procedures. Request the plan’s QDRO procedures and model language, if available.
- Clarify the settlement terms. Define the marital share, valuation date, gains and losses, payment timing, and any pension survivor-benefit issues.
- Prepare a draft order. A qualified professional drafts language that reflects both the agreement and the plan’s requirements.
- Seek plan preapproval when available. Many plans will review a draft before it is signed by the court, reducing the chance of a later rejection.
- Obtain the court order. The finalized document is submitted for judicial signature in the appropriate divorce matter.
- Submit the signed order to the plan. The plan administrator determines qualified status and then processes the division under its own timeline.
- Confirm completion and update records. Both parties should retain written confirmation and review beneficiary designations where appropriate.
What tax issues should Arizona couples consider?
A QDRO can create options, but it does not make retirement funds tax-free. Tax treatment depends on the type of plan, whether the recipient takes cash or completes a rollover, and the terms of the distribution.
For a spouse or former spouse who receives a distribution under a QDRO, the IRS notes that some or all of the amount may be eligible for a tax-free rollover into an IRA. If the recipient receives a taxable cash distribution, the amount is generally included in income. The IRS also states that amounts included in income from QDRO payments are not subject to the usual 10 percent additional tax on early distributions.
That exception should not be mistaken for a recommendation to take cash. A cash distribution can still create current income-tax consequences and reduce future retirement security. Before choosing a payout or offset arrangement, couples should consider their cash needs, tax brackets, investment timeline, and professional tax advice.
How mediation can improve retirement-division decisions
Mediation gives couples a private setting to examine retirement accounts alongside their other assets and future goals. Instead of treating a QDRO as a form to address after the major decisions are over, we help make retirement division part of the financial conversation from the beginning.
For complex matters, our divorce mediation professionals can coordinate with Certified QDRO Professionals, financial specialists, accountants, wealth advisors, and consulting attorneys as appropriate. That team-based approach can be especially valuable when a couple has a defined-benefit pension, executive compensation, a medical practice, substantial investments, or multiple real estate holdings.
Modern Mediation is led by Mara Linder, JD, MA, an Arizona attorney with more than 34 years of experience and a divorce mediator with more than 19 years of experience. We focus on helping couples make informed, durable financial decisions with privacy, structure, and respect.
Frequently Asked Questions
Can we divide a 401(k) in an Arizona divorce without a QDRO?
Usually, no. A divorce decree may establish each spouse’s rights, but most employer-sponsored plans need a qualified order before they can transfer or pay a former spouse’s share. The plan’s written procedures control the implementation steps.
Does every retirement account require a QDRO?
No. IRAs generally use a transfer incident to divorce rather than a QDRO, while public, military, and federal retirement systems may require different orders. Confirm the requirements directly with the plan administrator before preparing documents.
Who pays for a QDRO in an Arizona divorce?
The parties can decide how to allocate the cost in their settlement. Some couples divide the cost, while others assign it to one spouse based on the broader property agreement. The important point is to state responsibility clearly and include a process for cooperation.
Can a QDRO be prepared after the divorce decree is entered?
Yes, it can often be prepared after the decree, but waiting can add risk and delay. Account values may change, parties may become harder to locate, beneficiary issues can arise, and plan requirements may be overlooked. Addressing the process during settlement is usually more orderly.
Can a QDRO give a former spouse pension survivor benefits?
Potentially, but the order must address the issue correctly and the plan must offer the applicable benefit. Pension survivor rights are technical and can have significant long-term consequences, so they should be evaluated before the settlement is finalized.
Make Retirement Division Part of a Thoughtful Settlement
A QDRO is technical, but the decision behind it is deeply personal. If you are considering a private divorce process in Scottsdale, Paradise Valley, Phoenix, or elsewhere in Arizona, we can help you evaluate retirement accounts as part of a clear and financially informed settlement.
About Modern Mediation
Modern Mediation is a private, attorney-led divorce mediation firm serving couples throughout Arizona, including Scottsdale, Paradise Valley, Phoenix, and surrounding communities. We help couples navigate the personal and financial decisions that come with divorce through a thoughtful alternative to traditional litigation.
Founder Mara Linder, JD, MA is an Arizona attorney with more than 34 years of experience, a divorce mediator with more than 19 years of experience, and has helped more than 2,000 couples through divorce mediation and family transitions.
We frequently work with business owners, physicians, executives, professionals, and couples navigating real estate, investments, retirement assets, executive compensation, and other significant financial considerations.
Modern Mediation
7878 N 16th St, Ste 130-15a
Phoenix, AZ 85020
Phone: 480.780.3798
Schedule a Private Consultation with Modern Mediation
Disclaimer: Modern Mediation works exclusively as a mediator. The information in this article is provided for general educational purposes and is not legal advice. You should consult an attorney regarding your individual legal situation.
Disclaimer: Modern Mediation works exclusively as a mediator. The information in this article is provided for general educational purposes and is not legal advice. You should consult an attorney regarding your individual legal situation.