

Equity compensation can make an otherwise straightforward property discussion much more complicated. A stock option may have been granted during the marriage, may not vest until years later, and may depend on the employee spouse remaining with the company. That combination creates important questions about ownership, value, taxes, timing, and risk.
Dividing stock options in an Arizona divorce requires more than looking at the current share price or splitting a statement in half. Couples need to understand what the award was intended to compensate, when the marital community ended, what the employer’s plan permits, and how a proposed agreement will work when the options eventually vest or are exercised. This guide explains the issues Arizona professionals, executives, and business owners should address before reaching an agreement.
Are Stock Options Community Property in Arizona?
Often, at least part of a stock-option award is community property if it was earned through work performed during the marriage. The answer is not automatic for unvested awards because Arizona looks closely at whether the grant rewards past or current work, encourages future employment, or does both.
Arizona generally treats property acquired during marriage as community property, subject to statutory exceptions. In a dissolution, the court is directed to divide community property equitably, though not necessarily by dividing each individual asset in kind. That distinction matters when options cannot be transferred, have not vested, or are too uncertain to value reliably.
For stock options and similar executive benefits, the date of grant is important, but it is not the only relevant date. The vesting schedule, grant agreement, employer communications, performance period, and the date the dissolution petition was served can all affect the analysis.
Why Does the Purpose of the Stock Option Grant Matter?
The employer’s purpose is central because it helps distinguish compensation for work already performed from an incentive tied to work after the marriage ends. Arizona appellate decisions have treated unvested options similarly to other deferred employment benefits and have emphasized this purpose-based analysis.
In practical terms, couples should not assume that every option granted during the marriage is entirely divisible, or that every option vesting after separation belongs entirely to the employee spouse. A single grant can include both a community component and a separate-property component.
Documents that can clarify the award
- Equity incentive plan and stock-option agreement
- Grant notices and vesting schedules
- Offer letters, compensation summaries, and annual proxy materials
- Employer emails describing the reason for the award
- Performance reviews, retention agreements, or promotion materials
- Brokerage statements showing exercised, expired, and outstanding options
How Are Vested and Unvested Options Treated Differently?
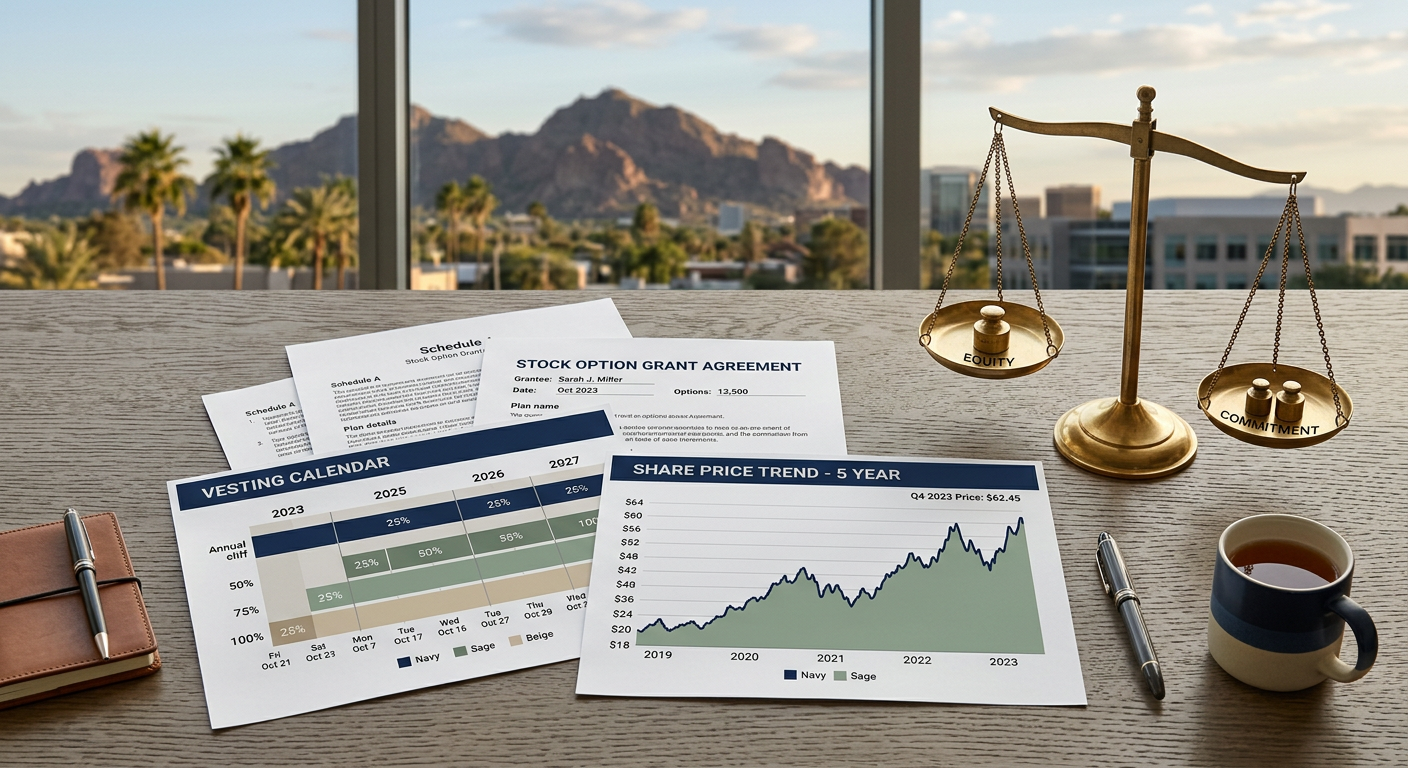
Vested options are usually easier to identify and address because the employee spouse has a present right to exercise them, subject to the plan’s terms. Unvested options are more complex because their eventual value may depend on continued employment, future company performance, a future liquidity event, or an expiration date.
| Type of Award | Primary Question | Common Planning Issue |
|---|---|---|
| Vested options | What is the net economic value? | Exercise costs and taxes |
| Unvested options | What work does the award compensate? | Community versus separate share |
| In-the-money options | What is the spread? | Timing of exercise or sale |
| Out-of-the-money options | Is there current value? | Future upside and expiration risk |
| Nontransferable options | Can ownership change hands? | Constructive trust or payout process |
A useful way to think about an option is that it is not the same as stock. An option is a contractual right to buy stock at a stated exercise price. Its economic value may be affected by the current stock price, the exercise price, remaining term, volatility, restrictions, and the possibility that the employee may forfeit it before vesting.
How Do Arizona Couples Allocate the Community Portion of Unvested Options?
When a grant spans both the marriage and the post-petition period, couples may use a time-based allocation method that reflects the employer’s purpose for the award. The appropriate approach depends on the specific grant, rather than a one-size-fits-all formula.
Arizona cases distinguish between approaches designed for awards that primarily compensate past or current performance and approaches designed to reward continued future service. In mediation, we help couples organize the relevant facts first, then work with appropriate financial, tax, or employment-benefit professionals when the estate warrants specialized analysis.
The goal is not to create artificial precision where an award remains uncertain. It is to create a clear, workable agreement that states what portion is being shared, how it will be calculated, when payment occurs, and who bears the economic consequences if the award changes.
Questions a settlement agreement should answer
- Which grants are included, identified by grant date and award number?
- What percentage or formula applies to each grant?
- Will the employee spouse keep legal title because the plan prohibits transfer?
- Who decides whether and when to exercise vested options?
- How will exercise costs, withholding, brokerage fees, and taxes be handled?
- What happens if the employee spouse leaves, is terminated, or the grant is forfeited?
- What reporting, notice, and payment deadlines will apply?
Considering a private resolution for complex executive compensation? When stock options, RSUs, deferred compensation, or a business interest are part of the marital estate, you can schedule a private consultation with Modern Mediation to discuss a thoughtful process for organizing the financial decisions ahead.
What Are the Tax Issues When Dividing Stock Options?
Taxes should be addressed before either spouse treats a projected option value as cash in hand. The federal tax treatment can differ based on the type of option, including nonqualified stock options and incentive stock options, as well as the structure and timing of the divorce agreement.
For nonstatutory options transferred incident to divorce, IRS guidance generally provides that the transfer itself does not create gross income for the transferring spouse. The spouse who later exercises the option generally recognizes the related income. That rule does not eliminate the need for careful drafting, payroll coordination, and individualized tax advice.
Couples should also consider withholding. An employer may issue wage reporting to the employee spouse even if settlement terms assign part of the economic benefit to the other spouse. A clear agreement can address anticipated tax obligations, reimbursement mechanics, tax-return cooperation, and the records both spouses will need later.
Can We Offset Stock Options With Other Assets Instead?
Yes. An offset can be practical when one spouse prefers certainty and the other wants to retain the options, but it only works when both spouses understand the assumptions behind the trade. Options can be volatile, illiquid, and subject to forfeiture, so their headline value may not reflect their true after-tax value.
For example, one spouse may retain a portfolio of options while the other receives a larger share of brokerage assets, cash, real-estate equity, or retirement assets. This approach can reduce the need for future contact, but it requires thoughtful comparison of liquidity, tax character, growth potential, and risk.
Our approach to financial expertise during divorce is especially helpful when a proposed trade involves different asset types. A dollar of pre-tax retirement money, a dollar of cash, and a dollar of speculative options do not necessarily have the same practical value.
What Happens if the Employer Will Not Transfer the Options?
Many employer plans prohibit direct transfer of stock options to a former spouse. That limitation does not necessarily prevent a couple from reaching an agreement, but it means the agreement must be designed around the plan rather than wishful assumptions.
Depending on the circumstances, the employee spouse may retain title while holding a defined share for the other spouse’s benefit. The agreement may require notice before an exercise event, establish how exercise funds are supplied, require prompt payment of net proceeds, and address cooperation with brokerage or payroll paperwork.
Those details are not minor. A vague provision can create conflict years after the divorce, particularly if the company is acquired, the stock price changes quickly, or the employee spouse changes jobs. For sophisticated estates, a private team-based mediation process can bring the right professionals into the conversation early, including tax advisors, financial analysts, and consulting attorneys as appropriate.
How Do RSUs, Restricted Stock, and Deferred Compensation Fit Into the Discussion?
RSUs are not stock options, but they often raise similar division questions. An RSU typically represents a promise to deliver stock or cash after vesting conditions are met, while a stock option gives the holder a right to purchase shares at an exercise price. Both may include service-based vesting and both can require an analysis of whether the grant rewards past work, future work, or both.
Deferred compensation, performance shares, annual bonuses, carried interests, and long-term incentive plans may add another layer. The right solution depends on the plan documents, payment dates, vesting requirements, tax treatment, and whether the benefit is connected to work performed during the marriage.
It is also important to view equity compensation in the context of the entire estate. Couples with significant retirement assets should coordinate these decisions with their approach to dividing retirement accounts and QDRO planning, rather than negotiating each asset in isolation.
What Can Couples Do Before Mediation Begins?
Preparation creates clarity and often reduces avoidable disagreement. Before the first substantive property discussion, gather the records needed to identify every grant and understand the terms. If either spouse has questions about the grant’s purpose, ask the employer’s stock-plan administrator for documents or explanations that can be shared appropriately.
- Create an inventory of every option, RSU, restricted-stock, bonus, and deferred-compensation award.
- Label each award as vested, unvested, exercised, expired, or forfeited.
- Collect grant agreements, vesting schedules, plan documents, and recent account statements.
- Identify the date of marriage, grant dates, vesting dates, and the date the divorce petition was served.
- Discuss whether a future-sharing arrangement or an asset offset better fits your priorities.
- Obtain individualized legal and tax advice before finalizing binding terms.
For couples in Scottsdale, Paradise Valley, Phoenix, and throughout Arizona, private mediation can offer a structured setting to evaluate those choices without turning every uncertainty into a courtroom dispute. Learn more about the experience and approach of Mara Linder, JD, MA, an Arizona attorney-mediator who has worked with more than 2,000 couples through divorce and family transitions.
Frequently Asked Questions
Are stock options split equally in an Arizona divorce?
Not necessarily. Arizona divides community property equitably, but that does not require a literal split of every award. The community portion of an option may be shared directly, offset with other assets, or handled through a future-payment arrangement.
Do unvested stock options count in divorce?
They can. The key question is whether the unvested grant was intended to compensate work performed during the marriage, to encourage future employment, or both. The grant documents and the employer’s stated purpose can be important evidence.
What is the difference between an option and an RSU in divorce?
An option gives the right to buy shares at a predetermined exercise price, while an RSU generally provides stock or cash when it vests. Both can be part of a divorce-property analysis, but their economics, taxes, and plan restrictions differ.
Can a former spouse receive stock options directly?
Sometimes, but many employer plans restrict direct transfers. If transfer is not allowed, a settlement may instead establish a process for the employee spouse to exercise or sell the relevant portion and distribute agreed net proceeds.
Should we use the current stock price to value options?
The current stock price is only one factor. A meaningful analysis may also consider the exercise price, vesting status, expiration date, transfer restrictions, expected taxes, and the risk that unvested options could be forfeited.
Make the Equity-Compensation Discussion More Manageable
Stock options do not need to derail a divorce settlement, but they do deserve careful attention. When both spouses have complete information and a realistic understanding of the risks, they can choose a solution that reflects their financial priorities, limits future ambiguity, and supports a more stable transition.
A well-designed agreement recognizes that executive compensation is not simply a number on a statement. It is a combination of employment terms, future uncertainty, tax consequences, and family financial goals. Taking the time to address those details can help preserve clarity, privacy, and control.
Discuss Your Equity Compensation in a Private Setting
If your divorce involves stock options, RSUs, deferred compensation, investments, or other complex assets, we can help you explore a calm, financially informed mediation process. Modern Mediation works with Arizona couples who want thoughtful decisions without unnecessary conflict.
About Modern Mediation
Modern Mediation is a private, attorney-led divorce mediation firm serving couples throughout Arizona, including Scottsdale, Paradise Valley, Phoenix, and surrounding communities. We help couples navigate the personal and financial decisions that come with divorce through a thoughtful alternative to traditional litigation.
Founder Mara Linder, JD, MA is an Arizona attorney with more than 34 years of experience, a divorce mediator with more than 19 years of experience, and has helped more than 2,000 couples through divorce mediation and family transitions.
We frequently work with business owners, physicians, executives, professionals, and couples navigating real estate, investments, retirement assets, executive compensation, and other significant financial considerations.
Modern Mediation
7878 N 16th St, Ste 130-15a
Phoenix, AZ 85020
Phone: 480.780.3798
Schedule a Private Consultation with Modern Mediation
Disclaimer: Modern Mediation works exclusively as a mediator. The information in this article is provided for general educational purposes and is not legal advice. You should consult an attorney regarding your individual legal situation.
Disclaimer: Modern Mediation works exclusively as a mediator. The information in this article is provided for general educational purposes and is not legal advice. You should consult an attorney regarding your individual legal situation.